Trustpilot logo
Rated Excellent - 4.5 out of 5
  1. Home
  2. Home insurance
  3. Contents insurance

Contents insurance

Insure your contents from £32* a year

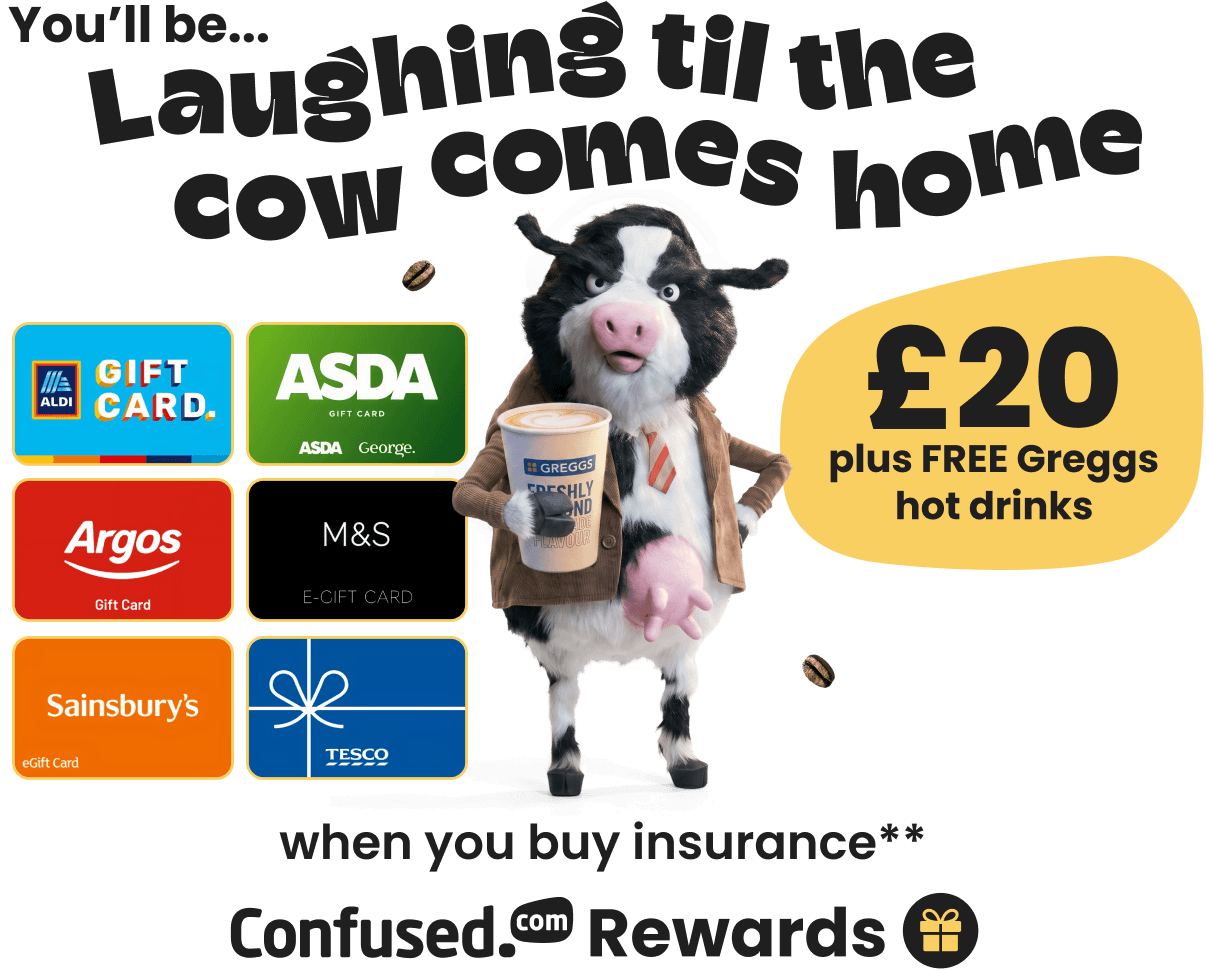
Confused.com Rewards: "You'll be laughing til the cow comes home." A black and white cow in a brown jacket and striped tie holds a Greggs coffee, beside gift cards for Aldi, Asda, Argos, M&S, Sainsbury's and Tesco. Get £20 plus free Greggs hot drinks when you buy insurance.

*10% of customers were quoted this amount or less for a contents insurance policy. Based on 108,805 quotes for contents-only cover on Confused.com, July–September 2026.
**Single annual policy. App only. Maximum claim limit. One regular hot drink per month for a year, only available via the Confused.com app. T&Cs apply.
[1]Correct as of July 2026

Compare up to 93 trusted insurance companies1 all in one place

What is contents insurance?

Contents insurance is a type of home insurance that covers your belongings for repair or replacement if they’re stolen, damaged, or destroyed by fire, or other unforeseen incidents like storms and flooding.

Contents insurance covers what’s inside your home but also things stored in an outbuilding, garage or garden. This includes virtually everything you would take with you if you were to move.

It’s different from building insurance, which protects the physical structure of your home (the walls, roof, fixtures, fittings and pipes).

You can take out contents and buildings insurance together as a combined house insurance policy, or you can take them out separately.

This gives you the freedom to pick and choose what you’re insured for.

Our home insurance expert, Matthew’s top tip:
"If you rent a furnished home, your landlord is normally responsible for insuring their own furniture and appliances. You only need to insure your own belongings, so check your tenancy agreement to see what's yours and what's theirs."

How much is contents insurance?

Confused.com customers were quoted £47*** on average for their contents insurance.

But exactly what you pay will vary. This is because the cost of contents insurance changes depending on a number of factors, like:

Contents value

The higher the value of the contents you insure, the more you’ll typically pay for your cover. Setting an accurate total means you avoid overpaying for cover you don’t need. It also means you’re not left out of pocket if you need to replace anything after a loss.

Contents value Average price of contents insurance***
£0-10k
£43
£10-15k
£46
£15-20k
£45
£20-25k
£44
£25-30k
£45
£30-35k
£47
£35-40k
£47
£40-45k
£53
£45-50k
£50
£75k+
£81

High value items

High-risk or high-value items are things like luxury watches, jewellery, high-spec laptops, or bikes. As these items can be a target for thieves and can cost a lot to repair or replace, insurers typically charge you more to insure them.

Insurers will ask you to list any items worth over £1,000 or bikes or laptops worth over £150.

The more high-risk items you insure, the pricier your premiums are likely to be.

Insurers usually have a limit on how much they’ll pay for one item. If you don’t list a high-value item, you may not be covered for its full value.

Number of high-risk items Average price of contents insurance***
0
£42
1
£50
2
£60
3
£70
4
£85
5
£103
6+
£146

Total number of rooms

Generally, the more rooms you have in your home, the more you’re likely to pay for your contents insurance. Insurers use the room count as a proxy to estimate the overall size of your property and how much stuff you’re likely to own.

The room count doesn’t include hallways or corridors.

Larger homes generally have more furniture, tech, and personal belongings, meaning the total cost of replacing everything in them is typically higher.

Number of total rooms Average price of contents insurance***
2
£54
3
£53
4
£44
5
£43
6
£45
7
£47
8
£49
9
£54
10
£57

Property location

Where you live directly affects your risk profile (how likely you are to make a claim). Houses in postcodes with higher local crime rates or areas more prone to natural hazards like flooding cost more to insure because the statistical chance of you making a claim is higher.

UK region Average price of contents insurance***
Greater London
£60
Greater Manchester
£52
Edinburgh
£44
Wrexham
£48
Cambridgeshire
£47
Cornwall
£45
Birmingham
£47

Property type

The type of property you insure has an impact on how your possessions are stored and how vulnerable they are to break-ins, flooding and other risks.

If you live in a property that’s deemed ‘higher risk’, it can increase the costs of your contents insurance.

Property type Average price of contents insurance*** Most common contents value***
Detached house
£59
£50,000
Bungalow (detached)
£46
£40,000
Semi-detached house
£49
£40,000
Terraced house
£48
£40,000
Maisonette
£48
£30,000
Flat
£45
£25,000
Our home insurance expert, Matthew’s top tip:
While detached homes are the most expensive to insure on average (£59/year), they also usually store double the average contents value (£50,000) of a flat (£25,000).

What does contents insurance cover?

What's covered

Risks and events typically covered What this means
  • Storms
Covers the cost of replacing belongings damaged by storms if a tree falls through your roof and damages your possessions, for example.
  • Fires
Covers your possessions against fire and smoke damage, lightning strikes and explosions inside the home.
Covers furniture, electronics, and other personal effects against water damage caused by heavy rain, rising water levels, or burst pipes.
  • Theft
Covers the cost to replace stolen belongings following a break-in, provided your property was securely locked with signs of forced entry. Theft claims can be costly, with the Association of British Insurers reporting that the average claim for theft reached a record £5,100 between April and June 2026, up 27% year-on-year.
  • Vandalism
Covers loss or damage to your personal property caused by intentional acts of vandalism or malicious harm committed by someone outside your household.
  • Escape of water
Covers damage to your possessions from things like burst pipes, leaking central heating systems and overflowing washing machines.
  • Impact damage
Covers your belongings against damage caused by things like falling trees, telegraph poles, or debris crashing into the property. Also covers strikes from vehicles.

What's not covered

Risks and events not typically covered What this means
  • Wear and tear
General deterioration or age-related breakdown, like a sofa fading or a laptop slowing down over time.
  • Poor maintenance
Damage resulting from a failure to keep up with regular home maintenance, such as checking pipes and guttering.
  • Items that exceed the single-item-limit
Individual high-value items worth over a set amount, that were not explicitly declared to your insurer. The set amount varies from insurer to insurer, so check your policy documents to make sure your valuables are covered.
  • Unforced entry
Theft occurring when doors or windows were left unlocked, showing no physical signs of forced entry.
  • Accidental damage
Everyday mishaps, like spilling drinks or dropping items. Accidental damage cover can be added as a policy add-on, though.
  • DIY
Damage caused by attempting home repairs or electrical work yourself without professional qualifications.
  • Deliberate damage
Intentional damage caused to your belongings by you or anyone else living in your household.
  • Items outside of the home
Belongings lost, stolen, or damaged outside the property. Personal possessions insurance can be added as an add-on to cover your property outside the home.
  • Pet damage
Damage caused by domestic pets, including things like chewing or scratching furniture. Indirect damage, like dropping a laptop after tripping over your cat, will be covered, though. See how you can protect your home from pet damage with our guide.
Damage or contamination caused by pests like mice, rats, squirrels, or insects.
  • Theft or damage of company equipment
If your employer supplies you with working from home equipment like a monitor or laptop, damage to or theft of this equipment is their responsibility. If you use your own equipment, contents insurance will cover you, however.
A tip from our expert, Matthew:
Standard contents insurance is designed for unexpected disasters, not everyday wear and tear or gradual deterioration. Common mishaps like spilling wine on the sofa, dropping a laptop, or taking your phone out of the house won't be covered unless you add optional add-ons like accidental damage insurance or personal possessions cover.

What items are covered?

Items typically covered What this includes
  • Technology
TVs, phones, laptops, tablets, smart speakers, and audio equipment - when inside your home.
Rings, watches, and chains. Items valued over £1,000 need listing separately. Or get specialist watch insurance.
  • Furniture
Tables, sofas, beds, sideboards, and freestanding wardrobes.
  • Home appliances
Freestanding kitchen appliances damaged by incidents like burst pipes or theft (excludes internal technical faults). Learn more about kitchen appliance insurance.
  • Cash & important documents
Physical cash or important documents (like passports) lost, stolen, or destroyed while inside the house.
  • Clothes
Everyday clothes and footwear that are destroyed or stolen.
  • Soft furnishings
Carpets, rugs, curtains, cushions, and bed linen.
  • Food
Food inside your fridge and freezer is spoilt or stolen during a claimable event.
  • Equipment for hobbies
Specialist hobby gear like golf clubs or scuba gear securely stored inside your home, shed or outhouse.
  • Sentimental/precious items
High-value artworks or ornaments (standard policies cap single items at £1,000 unless declared).
  • Items in gardens and outbuildings
Belongings kept in locked outbuildings, like garden furniture, tools, and lawnmowers.
A tip from our expert, Matthew:
Most policies put a limit on the amount you can claim for a single item - typically around £1,000. If you have contents worth more than this, you may need to pay the extra to replace them if they’re damaged or destroyed. High value contents insurance can help you fully cover them, though you’ll normally have to pay a little extra to add this cover onto your policy.

Get £20 to spend with 100+ brands plus year-round hot drinks when you buy**

How to claim
Six Greggs hot drink cups glowing

**Single annual policy. App only. Maximum claim limit. One regular hot drink per month for a year, only available via the Confused.com app. T&Cs apply.

Contents insurance add-ons

Want to give your contents insurance a boost? Optional add-ons let you tailor your cover to your needs, for an additional fee. 

Here's the extras you can bolt on to your cover:

Home building insurance icon

Accidental damage insurance

Insures your contents against accidental damage or destruction.

Scenarios it could cover include:

  • Dropping your laptop down the stauits
  • Spilling red wine over your new carpet
  • Smashing a glass dining table
  • Drilling through pipes while doing DIY
  • Smashing a window

Without it in place, your contents are only insured against things like flood damage, burglary and fire. Any mishaps wouldn't count as claimable events.

Learn more about accidental damage cover

Mobile insurance icon

Personal possessions cover

This covers items you might carry with you while you're away from home

It could cover:

  • Phones
  • Jewellery
  • Laptops
  • Earphones
  • Watches

Without it in place, your contents are only insured while they're in your house. You wouldn't be able to claim if you lost your phone while out and about.

Learn more about personal possessions insurance

To compare quotes for policies that include these add-ons, simply select the extras you want when you get a quote with us.

Is contents insurance mandatory?

No, contents insurance is not mandatory.

Unlike buildings insurance, which mortgage lenders usually require you to have as a condition of your loan, contents insurance is entirely optional. However, having a policy in place is generally a good idea, as it helps to protect your belongings against unexpected loss, theft, fire, or flood damage.

Without contents insurance, you would be faced with the cost of replacing or repairing your belongings yourself if something like a flood or fire ruined your home and your possessions in it.

And between your clothes, tech, appliances, and furniture, your belongings are worth more than you might realise!

Who needs contents insurance?

Whether you rent or own your home, having some sort of contents insurance policy in place ensures your belongings are covered:

Homeowners

As a homeowner, you’re responsible for both the building and everything inside it. Contents insurance could help you cover the cost of replacing your possessions as a result of a leak or fire.

Leasehold flat owner

Though the freeholder or building management company usually arranges the structural buildings insurance, your possessions are your responsibility.

Tenant

You aren't responsible for insuring the walls or roof - that's your landlord's job. You only need to protect your personal belongings, furniture, and gadgets.

Landlord

If your property is fully furnished, landlord contents insurance can help cover your furnishings against damage inflicted by your tenants.

Students

Laptops, uni gear, and phones are easy targets. Student contents insurance can cover what’s inside your room, whether you're living in halls or a shared student house.

Holiday home owner

If you’ve kitted out your holiday home for guests, cover the contents whether it’s occupied full time or  left empty for long stretches.

Tenant in shared house or flat

Standard contents insurance should cover you if you live in a shared house. Just check your theft exclusions, as insurers usually require high-value items to be kept in your locked bedroom to be covered against theft.

How much contents insurance do I need?

This depends on the number and value of your belongings. Generally speaking, the more belongings you have, the more cover you’ll need.

Putting a figure on the total value of your belongings can be tricky, but here are some steps you can take to accurately work out how much contents insurance you need:

Go from room to room in your house and list anything that you'd take with you if you were moving out.

Once you have the list, do a mental check on the value of each item and start to add it together. For more specific mid-high-value items you might want to quickly research the item online and make a note of the amount.

If you want some help totting the figures up, add the amount into our contents calculator. The calculator splits the contents up room by room and works out the total value.

Confused.com data shows that the average value of contents insured on a contents-only policy is £0-10,000.

For contents insured on a combined buildings and contents policy, the total goes up to £45,000 - £50,000. The big difference in sums insured tends to be due to the value of possessions, number of rooms and occupants being higher across combined buildings and contents insurance policies.

Tell us the value of items in your living room that you need cover for

Please enter a valid number

What our home insurance expert says

"When you're working out the value of your contents, don't forget to account for anything you've got tucked away in cupboards, storage, a loft or attic, garage, shed, garden or outbuildings.

“It can be easy to forget these items because you can't see them, but the value of items like sporting equipment, tools and some expensive BBQs can soon reach hundreds or even thousands of pounds. Some insurers do include a limit on the standard value covered for items stored in garages or outbuildings, so check the policy details if you're concerned about fully insuring items in these areas of your home.

Remember:
If any individual items are worth more than £1,000 or you have bikes worth more than £350, list them in the high-risk section when you're getting a quote.
Matthew Harwood, Home & lifestyle insurance expert at Confused.com
Home & lifestyle insurance expert Confused.com logo

What do I need to get a contents insurance quote?

To get a contents insurance quote follow these steps:

Number 1 icon

Tell us about your home

To start, we’ll need a few details about the property - such as the number of rooms and how its home is heated.

Number 2 icon

Tell us about your home security

Let us know if the property is your main residence, whether there’s an alarm installed, and what types of locks are fitted to your external doors.

Number 3 icon

Tell us about you, and your policy history

Tell us whether you own or rent the property, when you purchased it, how much contents insurance you need and how many years of No Claims Bonus (NCB) you have.

Note: A longer NCB can help reduce your premium!

White number 4 on a black background

Lastly, who is the policy holder?

We’ll need to know who the main policyholder is, including their full name, date of birth, occupation, marital status, contact details, and how long they’ve lived in the UK.

See what our customers have to say:

4.5 green stars

4.5 rating based on 17110 reviews
as of 20/10/2026

Trustpilot logo

What are Defaqto ratings and why should you care about them?

Defaqto ratings are independent star ratings that can help you compare financial products, like contents insurance. They look at the features and benefits included in a policy, with higher ratings generally indicating a more comprehensive level of cover,

They can be useful when comparing policies because they give you a quick way to understand what the level of cover a product offers in comparison to its price.

Defaqto star ratings from 5 to 1

Learn more about Defaqto ratings for home insurance.

How to make a contents insurance claim

If you need to make a contents insurance claim, follow these steps to get started:

  • Make sure you’re safe
    Deal with any immediate risks first. For example, you should turn off any water if you have a leak, or contact the police if your home has been broken into. If there is no danger, this step may not be necessary.
  • Record any evidence
    Take photos or videos of the damage and make a list of anything that has gone missing or damaged. Keep receipts, invoices, and any other proof of ownership or value.
  • Contact your insurer
    Contact your insurer and tell them what has happened, and submit your claim with the supporting evidence you recorded (your photos, videos, receipts etc). Include your police crime reference number if you have one.
  • Let your insurer assess the claim
    Your insurer will review the claim and may arrange an inspection or ask for further evidence. If your claim is approved, they’ll explain to you how your belongings will be replaced, repaired, or paid for.
  • Receive your payout
    Once your insurer accepts your claim and pays out, you can continue replacing or repairing your items. If your claim is rejected, find out why this is and appeal to your insurer. They may just need a bit more information or evidence to support their decision.
A tip from our expert, Matthew:
Keep photos, receipts and other proof of your belongings in a safe place before anything goes wrong. Having this evidence ready can make the claims process much quicker and easier.

How does house contents insurance pay out?

Policies could pay out in a couple of ways, depending on the type of cover included in the contents insurance policy:

Cover type How it works Example
New for old
New for old contents insurance is the most common type of cover. If your possessions are stolen, damaged, or destroyed, the insurer will pay out the cost to replace them with a brand-new equivalent item at today's retail prices.
If a 5-year-old TV that you originally bought for £500 is stolen, the insurer will pay out enough money for you to buy a brand-new model of a similar specification currently on the market for £500.
Indemnity (current market value)
Indemnity, also known as current market value cover, calculates your payout based on what your item is worth at the time it is lost or damaged. It factors in wear, tear, and depreciation, meaning that the payout reflects the item’s current value based on age and condition rather than its original price.
If that same 5-year-old TV is stolen, the insurer will estimate how much it depreciated over 5 years, including the factors above. The insurer may only pay out its current second-hand value (e.g. £100), leaving you to pay the remaining cost if you want to buy a brand-new replacement.

Most policies offer new-for-old cover, but all policies are different, so it’s worth checking.

If you don’t see it mentioned anywhere when you’re researching your chosen policy, check the policy schedule or key facts document under ‘Basis of claims settlement’ for the type of cover included. Unless “new for old” is specifically stated, claims will be calculated using current market value calculations.

The Association of British Insurers (ABI) recommends insuring your contents for the cost of replacing them as new, not their current value, and reviewing your sum insured regularly, especially after buying expensive items or after birthdays and Christmas.

Did you know?
While indemnity cover policies may have cheaper premiums, they deduct the value for age and wear, leaving you to pay the difference if you want a brand-new replacement. Always check if a policy is new-for-old or indemnity before buying.

Need more help?

Do I need contents insurance as a tenant?

Contents insurance isn’t a legal requirement for renters, but it can help protect your personal belongings against risks like fires, theft, and water damage. Your landlord's insurance generally covers the building and any furnishings within the property, but not the things you specifically own.

Do I need contents insurance as a student?

Similarly to tenants, contents insurance is not a legal requirement for students. However, with an estimated third of the UK students falling victim to crime, it can help cover your valuables - like your laptop phone or bike - against fire, theft, or flooding while you’re living at uni.

Tip: If you are living in halls, check whether insurance is already included and what it covers before buying your own policy.

Does contents insurance cover mobile phones?

It depends. Most policies cover your phone against risks like fire, theft or flood damage if these occur while you’re at home. If your phone is stolen while you’re away from home, you’d need to have personal possessions insurance in place to cover it.

Most contents insurance policies come with a single item limit too. This is the maximum amount you can claim for a single item. If you have a top-of-the-range phone, its value might exceed this limit, meaning you wouldn’t be able to claim for its full value. Check your policy’s single item limit to help avoid scenarios like this, and look into high-value contents insurance if you need additional cover.

How soon can you claim on contents insurance?

You can usually claim on your contents insurance as soon as it starts. The incident you’re claiming for must have occurred while your policy was in place, though.

Before making a claim, ensure you check your policy and gather any evidence, photos, receipts or a crime reference number if you have one. This can help speed up the claims process and get your possessions replaced as soon as possible.

Are carpets covered by contents or buildings insurance?

Yes, contents insurance will generally cover damage to carpets in your home.

That’s because carpets aren’t usually considered a permanent part of the property - they can be lifted, replaced, or moved without making structural changes to your home.

Any types of flooring that are fixed in place, such as tiles, laminate or wooden flooring, are different, however, and are usually covered under buildings insurance. This is because they’re attached to the property and cannot be easily removed without causing damage to the structure.

How does excess work on contents insurance?

Your excess is the amount you pay towards a claim. It is made up of two types:

Compulsory excess: This is a fixed amount set by your insurer that you cannot change.

You must pay this amount every time you make a claim.

Voluntary excess: This is an optional amount you choose when taking out a policy. The more you choose to pay, the cheaper your policy might be. You’ll have to pay this amount every time you claim too.

For example, if your compulsory excess is £100 and you select a voluntary excess of £100, your total excess is £200. This is the amount you’d pay to make a claim.

Should I claim on lower-value items?

For low-value items, it's almost always cheaper in the long run to pay for the replacement yourself rather than making a claim.

This comes down to two factors:

  • Your excess
    If your total combined excess is £200, and the item you’re claiming for only costs you £100, it’d be cheaper to just replace the item yourself. Contents insurance is really worth claiming on when the value of the item you’re claiming for exceeds your excess.
  • Your claims history
    If you make a claim, your premiums are likely to be higher when you come to renew your policy. This is because insurers reward low-risk customers with better value premiums. If you’ve made a claim in the near past, your risk profile increases, and you’re charged more for your cover as a result. You’d also lose any no-claims bonus you might have accrued, which can push your premiums up even higher.

Types of home insurance

Contents insurance guides to help you

Explore more guides

***Important information

Cost of contents insurance. Based on Confused.com data, July-September 2026 standalone contents insurance policies median cost of £47.30.

Contents total value affects policy price. Based on Confused.com data, Q3 2026 standalone contents insurance policies median cost.

Number of high-risk items affects policy price. Based on Confused.com data, Q3 2026 standalone contents insurance policies median cost.

Property total room count (excluding hallways and corridors) impacts insurance price. Based on Confused.com data, Q3 2026 standalone contents insurance policies median cost.

Property location determines policy cost. Based on Confused.com data, Q3 2026 standalone contents insurance policies median cost.

Property type determines policy cost. Based on Confused.com data, Q3 2026 standalone contents insurance policies median cost.

Property type dictates declared contents value across contents-only quotes: Detached house (£50,000; 9,847 quotes), Detached bungalow (£40,000; 3,517 quotes), Semi-detached (£40,000; 23,798 quotes), Terraced (£40,000; 23,553 quotes), Maisonette (£30,000; 1,095 quotes), and Flat (£25,000; 48,235 quotes). Based on Confused.com data, July–September 2026.

Compare contents insurance quotes

Get a quote