
Insuring an ice cream van involves more than standard van cover, so we’ll explain what you need to protect both your vehicle and business.
Key takeaways
- Standard van insurance covers your vehicle on the road but doesn't cover your business.
- Ice cream van insurance typically costs around £1237 a year compared to £721 for standard van insurance. This extra cost is worth it to protect your business and equipment.
- You'll usually need a street trading licence from your council and some form of public liability cover before you're legally allowed to trade from a public spot.
What is ice cream van insurance and do you need it?
Ice cream van insurance lets you drive and trade legally. It also protects your business if things go wrong.
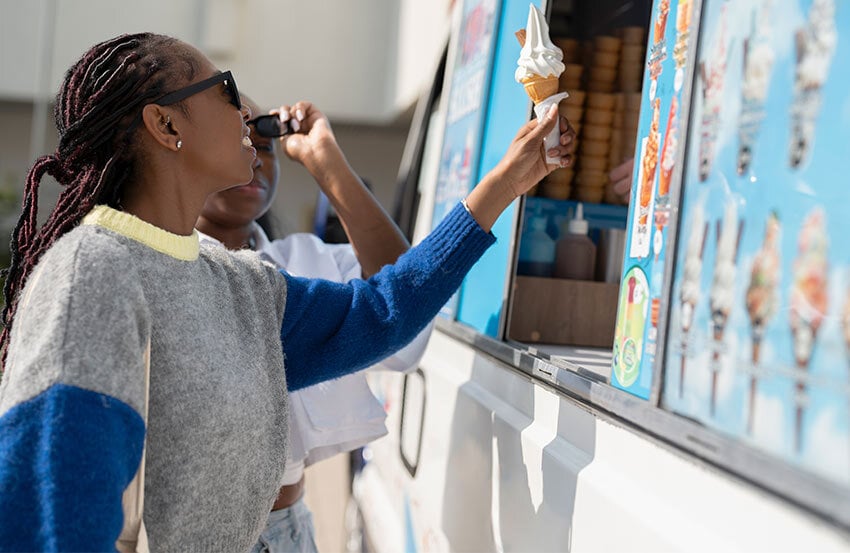
You need it if you sell to the public, as insurers consider selling ice cream to be commercial use of the van. This means a private or van insurance policy won't hold up if you need to claim.
What does standard ice cream van insurance cover?
Whether you're insuring an ice cream van or another type of van, you'll have 3 levels of cover to choose from:
| Level | What it covers |
|---|---|
|
Third party only
|
Damage or injury you cause to other people, vehicles or property. Legal minimum level of insurance needed to drive on UK roads - but rarely available to buy directly for commercial use.
|
|
Third party, fire and theft
|
The above, plus your own van if it's stolen or damaged by fire.
|
|
Fully comprehensive
|
The above, plus damage to your own van in an accident, regardless of fault.
|
These levels of cover protect the van, but they don’t necessarily cover the rest of your business, such as your freezer, stock, till or a customer who falls ill. That’s where you may need additional business cover.
The extra cover most ice cream van traders might need
A specialist or business van insurance policy can usually be tailored to include a range of cover options. Some policies include hire and reward cover, but not all do. If it isn’t included, you may need to arrange separate business insurance.
| Cover | On a standard van policy? | Why it matters |
|---|---|---|
|
The van itself
|
Included
|
Accident, fire and theft damage to the vehicle.
|
|
Public liability
|
Not included
|
Covers claims if a customer is injured or their property's damaged at your van -most councils and event organisers won't let you trade without it.
|
|
Employers' liability
|
Not included
|
Legally required if you employ anyone, even a Saturday assistant -minimum £5m cover under the Employers' Liability Act.
|
|
Business equipment & stock
|
Not included
|
Covers your freezer, generator, till and ingredients if they're stolen, damaged, or spoil after a breakdown.
|
|
Personal accident
|
Optional add-on
|
Pays out if you're injured and can't work -worth considering if you're a sole trader with no sick pay.
|
|
Legal expenses
|
Optional add-on
|
Covers legal costs for disputes not covered elsewhere, including contract or licensing disputes.
|
How much does ice cream van insurance cost?
Our data shows that ice cream van insurance costs around £1,237* a year on average. That’s more than the £721 for a standard van. Why? You’ve got valuable equipment on board, plus you’re often parked near people, especially children.
So, what affects your quote?
-
Where you trade: Busy city spots mean a higher risk of accidents, so your insurance can cost more.
-
Your driving history: A clean record with no claims for a few years can really bring your price down.
-
Optional extras: Things like public liability, stock cover and employers’ liability are usually added on top of your main policy price.
-
Security: Alarms, immobilisers and parking off-street overnight can reduce the risk of theft and lower your premium.
-
How much you drive: Insurers look at whether you trade seasonally, part-time or all year round.
How to bring the cost of ice cream van insurance down?
-
Compare before you review: Loyalty rarely pays with commercial van insurance. Get quotes from different insurers each year rather than simply auto-renewing.
-
Improve your van’s security: An alarm, immobiliser and off-street parking overnight can all help lower your premium.
-
Build a no-claims bonus: Under-declaring could invalidate a claim, while over-declaring means paying for cover you don’t need. Give your insurer a realistic estimate.
-
Improve your van’s security: Each claim-free year can earn you a discount at renewal. For smaller repairs, paying yourself could sometimes work out cheaper than making a claim.
-
Bundle your cover: Some insurers may offer a better deal when you combine your van and business insurance.
Our guide on how to get cheaper van insurance goes into more detail.
How to make a claim on your ice cream van insurance
Here’s how to make a claim and what to expect:
- Take photos: Photograph any damage, injuries or spoiled stock as soon as it’s safe to do so.
- Contact your insurer: Tell your insurer about any theft or accident as soon as possible. If the police are involved, you may also need a crime reference number when making your claim.
- Explain what happened: Give a full and accurate account of the incident. Inconsistent or missing details could delay your claim or affect the outcome.
- Keep your evidence: Hold on to receipts and other proof of your losses, particularly for stock, equipment or lost trading days.
- Understand who handles your claim: Your insurer may appoint a loss adjuster to assess the damage and help the insurer determine how much your claim is worth. You can also appoint a loss assessor yourself. They work on your behalf, helping you prepare and manage your claim and liaising with your insurer. You normally pay their fees yourself.
- Receive your payout: Once your claim has been assessed and approved, your insurer will deduct your excess and pay you the amount you’re owed.
Check the specifics of your policy with your insurer, as claims processes and requirements can vary.
FAQs
Is public liability insurance a legal requirement for ice cream van traders?
Public liability insurance isn’t a legal requirement, but most councils, event organisers and landowners will require proof of public liability cover before they'll let you trade on their land.
Do I need a licence to sell ice cream from a van?
Usually, yes. If you're trading on public land, you'll need a street trading licence from your local council. Trading on private land instead requires the landowner's permission..
Can I insure an ice cream van on a temporary or seasonal basis?
Yes - many insurers offer policies that reflect part-time or seasonal trading. Be upfront about how many months a year you're actually on the road, as it affects your price. You may want to look into temporary business van insurance.
*Confused.com data August-October 2026.
 cookie usage